


Your employer-sponsored retirement plan may be one of your most important assets during retirement. That’s why it’s important to make the most of it by saving as much as you can now. So, ask yourself: Am I saving enough for the future I envision?
In 2026, you’ll be able to contribute $24,500 plus an additional catch-up amount if you are age 50 or older. See the chart below for details by age.
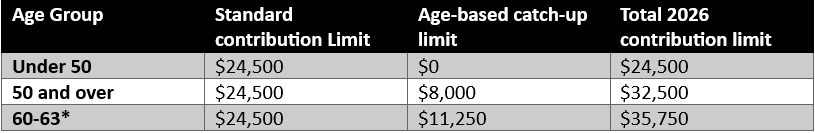
*The SECURE 2.0 Act of 2022 increases the catch-up limit for participants who attain age 60-63 during the calendar year. In the year the participant attains age 64, the limit returns to the age 50 catch-up limit. Check with your plan sponsor to see if this new catch-up limit is available in your plan.
Mandatory Roth catch-up contributions
Starting in 2026, if you’re age 50 or older and earned more than $150,000 in Federal Insurance Contributions Act (FICA) wages from the same employer in the prior year, you must make catch-up contributions to your retirement plan as Roth after-tax contributions. If this applies to you, you’ll receive additional communication.
If you earned less than that amount, you may continue to make catch-up contributions on a pretax or Roth basis.
For more details
For more information, click here to view a flyer, or visit LincolnFinancial.com/BalladSchedule to schedule a meeting with a Lincoln Financial retirement consultant.
